| |
 | | OCTOBER 2026 NEWSLETTER | |
 |
| Hi everyone, Welcome to our October update! As we head towards the end of 2026, there’s plenty happening across New Zealand’s property and finance markets. House prices remain under pressure in many parts of the country, interest rates have started moving upwards, and with the general election just around the corner, there’s plenty for buyers and homeowners to consider. The good news is that opportunities remain, particularly for first-home buyers and those looking to make their next move. This month, we’re looking at what’s happening in the property market, where interest rates could be heading, and why spring is a great time to review your mortgage, insurances and KiwiSaver. | | THIS MONTH AT A GLANCE  National Median Price $755,000  2.3% annually
| | |  Property Sales 5,752 11.6% annually | | |  Official Cash Rate 2.75% Following this week’s decision to hold | | Sources: September 2026 REINZ market report and Reserve Bank of New Zealand. | |
| HOUSING MARKET New Zealand property market update The latest figures show New Zealand’s housing market continues to move at different speeds, with softer conditions across much of the North Island while parts of the South Island are proving more resilient. The national median sale price for September was $755,000, down 2.3% compared with the same time last year. Sales volumes were also down 11.6%, with 5,752 properties sold nationwide. Properties are taking an average of 46 days to sell, while available listings have increased by 10.7%. For buyers, this means more choice, less pressure to make rushed decisions and, in many cases, greater room to negotiate. For sellers, realistic pricing and good presentation remain important. Let’s break this down further by selected regions around New Zealand. | |
| REGIONAL PROPERTY MARKET SNAPSHOTS QV average residential values, September 2026. Changes are over the three months to September unless otherwise specified. | HOW VALUES MOVED Three months to September 2026, QV average value | | Lower Hutt* | | | | −6.2% | | Porirua | | | −5.5% | | South Wairarapa | | | −4.1% | | Wellington City | | | −3.0% | | Auckland | | | −2.5% | | Masterton | | | −1.2% | | Otago | | | +1.9% | | Carterton | | | +2.2% | | Queenstown | | | +3.1% | | | * Lower Hutt is the change since 1 January 2026, not three months. | | WELLINGTON & HUTT VALLEY * Lower Hutt is the change since 1 January 2026. The region itself continues to experience challenging market conditions. Wellington City property values fell approximately 3% over the three months to September, while Porirua recorded a larger decline of 5.5%. Closer to home, Lower Hutt values are down 6.2% since the start of the year. While this isn’t ideal news for those looking to sell, it can create opportunities for first-home buyers and homeowners wanting to upgrade. If you’re selling and buying in the same market, the price difference between properties can matter as much as the sale price of your own home. We have certainly seen properties within these price ranges prove popular, with strong enquiry from first-home buyers looking to secure their first home. | | WAIRARAPA Masterton · Carterton · South Wairarapa The Wairarapa continues to show some interesting differences between its local markets. | AREA | AVERAGE VALUE | 3 MONTHS | | Masterton | $565,252 | −1.2% | | Carterton | $601,088 | +2.2% | | South Wairarapa | $705,458 | −4.1% | Carterton has been a relative bright spot, while Masterton and South Wairarapa have experienced softer conditions. For those considering a move to the Wairarapa — whether for lifestyle, affordability or investment — there are still opportunities worth exploring. | | AUCKLAND Auckland remains a buyer-friendly market in many areas. With plenty of properties available and buyers taking longer to decide, those looking to enter the market or move up the ladder may find themselves in a stronger negotiating position. | | QUEENSTOWN & OTAGO Otago +1.9% over the quarter Queenstown continues to stand out from much of the country. This highlights how differently regional markets are performing, with local demand, employment opportunities and housing supply all influencing property values. | | What does this mean for you? If you’re considering buying, now could be a good time to explore your options. More properties on the market and softer prices in many regions mean buyers can often take a more considered approach. The important thing is to understand your borrowing capacity, have your finance organised and be ready to act when the right property comes along. With lower sales turnover nationwide, many banks are also turning applications around faster than usual for this time of year — helpful if you like to move at short notice. | Source: QV September 2026 property value data and REINZ September 2026 market report. QV percentage movements are over three months unless otherwise specified. | |
| INTEREST RATES Interest Rates – Where Are We Heading? |  | After a period of falling interest rates, we’ve started to see a change in direction. The Reserve Bank increased the Official Cash Rate (OCR) by 0.25% in September, bringing it to 2.75%, following an earlier increase in July. Renewed inflationary pressures and higher wholesale funding costs have contributed to changes in mortgage pricing, with some banks already lifting selected fixed rates. Interestingly, not all fixed rates have been moving in the same direction. Banks remain competitive across certain terms, particularly around the two-year fixed period. What could happen next? The next OCR announcement was made on 28 October, and this came as some surprise to many. Some bank economists were forecasting a lift, but it was held at 2.75% this time, wanting a more gradual change to manage inflation. Their messaging still points to future lifts being needed, including December. While nobody can predict exactly where interest rates will go, we believe borrowers should give more consideration to repayment certainty rather than automatically choosing the shortest fixed term available. For many homeowners, fixing for two or three years may offer a sensible balance between certainty and flexibility. That doesn’t mean longer is always better. The right structure depends on your circumstances, future plans and how comfortable you are with potential rate changes. Is your mortgage coming up for refixing? If your mortgage is due to roll off its current fixed rate in the coming months, it’s worth reviewing your options now. We can help you compare available rates, negotiate with your existing lender where appropriate, and consider whether splitting your mortgage across different fixed terms could be beneficial. A small difference in your interest rate can make a meaningful difference to your repayments over time. | | | WHAT’S COMING UP? New Zealand’s General Election – 7 November |  | With the general election just around the corner, housing and the wider economy are likely to remain key talking points. Housing affordability, investment property rules, taxation and economic growth are all areas that homeowners, buyers and investors will be watching closely. Periods of political uncertainty can sometimes lead people to put major financial decisions on hold while they wait to see what happens. However, it’s worth remembering that property markets are influenced by a wide range of factors, including interest rates, employment, household incomes and housing supply. While the outcome of the election may influence future housing and economic policy, it won’t necessarily result in immediate changes to property prices or mortgage rates. We’ll continue to keep an eye on developments and what they could mean for our clients as we head into 2027. | | |
 Jo Vivian Mortgage Adviser  Dawn Whiteside Mortgage Adviser | FIRST-HOME BUYERS Opportunities are still out there Despite the uncertainty in the market, there are some positives for those looking to purchase their first home. With more properties available and less competition in many areas, first-home buyers may have more opportunity to negotiate on price and purchase conditions. KiwiSaver, low-deposit lending options and Kāinga Ora First Home Loans may also help eligible buyers get into their first property. Buying your first home can feel overwhelming, but it doesn’t need to be. We can help you understand how much you could borrow, work through your deposit options, obtain pre-approval and guide you through the process right through to settlement. Whether you’re just starting to save or already attending open homes, we’re always happy to have a chat. | |
 | | THIS MONTH’S BLOG Spring Clean Your Finances – Is It Time for a Financial Health Check? Spring is traditionally the time for clearing out the clutter and getting everything organised around the house. But when was the last time you gave your finances the same attention? Your mortgage, insurances and KiwiSaver are three important parts of your financial wellbeing, and what worked for you a year or two ago might not be the best fit today. Interest rates move, property values change, families grow and financial priorities evolve. Your mortgage Are you on a competitive interest rate? Is your loan structured to suit your current circumstances? Could you be making better use of offset accounts, revolving credit or additional repayments? Your insurance Does your life, trauma, income protection, health, house and contents cover still meet your needs? Are you paying for cover you no longer require, or are there gaps you haven’t considered? Your KiwiSaver Is your fund still appropriate for your goals and timeframe? Are your contributions working towards your long-term objectives, whether that’s buying your first home or preparing for retirement? Taking the time to review these areas could help identify unnecessary costs, improve your financial protection and ensure you’re making the most of your money. With mortgage and insurance expertise under one roof, our team can help you take a fresh look at your finances and get organised for the year ahead. | | |
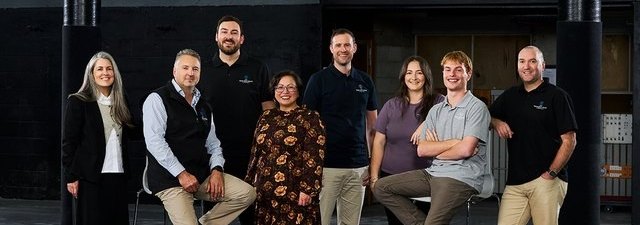 | | OUR INSURANCE TEAM Protecting what matters most Having the right mortgage is important, but so is protecting your home, income and family should the unexpected happen. Our dedicated insurance team works alongside our mortgage advisers to help clients review their personal and general insurance needs. Whether it’s life insurance, trauma cover, income protection, health insurance or reviewing your existing policies, Allister and Thurl are available to help. | | | | |
   | As we head towards the end of the year, now is a great opportunity to take stock of your financial position and make sure you’re well prepared for 2027. Whether you’re looking to purchase your first home, refinance, review your mortgage structure, explore investment opportunities or make sure your insurance is still right for you, our team is here to help. And if you have friends, family or colleagues who could benefit from some mortgage or insurance advice, we’d always appreciate the opportunity to help them too. Thanks again for your continued support, and we look forward to helping you with your property and financial goals. The Team at The Mortgage Advice Company Part of Your Tomorrow | | | | You are receiving this email because you recently used our services, and we’d like to keep you up-to-date with market trends, industry insights and tips. View in browser | Unsubscribe © The Mortgage Advice Company 2026. All rights reserved. | | |
| This newsletter contains general information only and does not constitute personalised financial advice. Property market figures are broad indicators and may not reflect individual properties. Interest rates, economic forecasts and lending criteria can change. Any financial decisions should take account of your individual circumstances. |